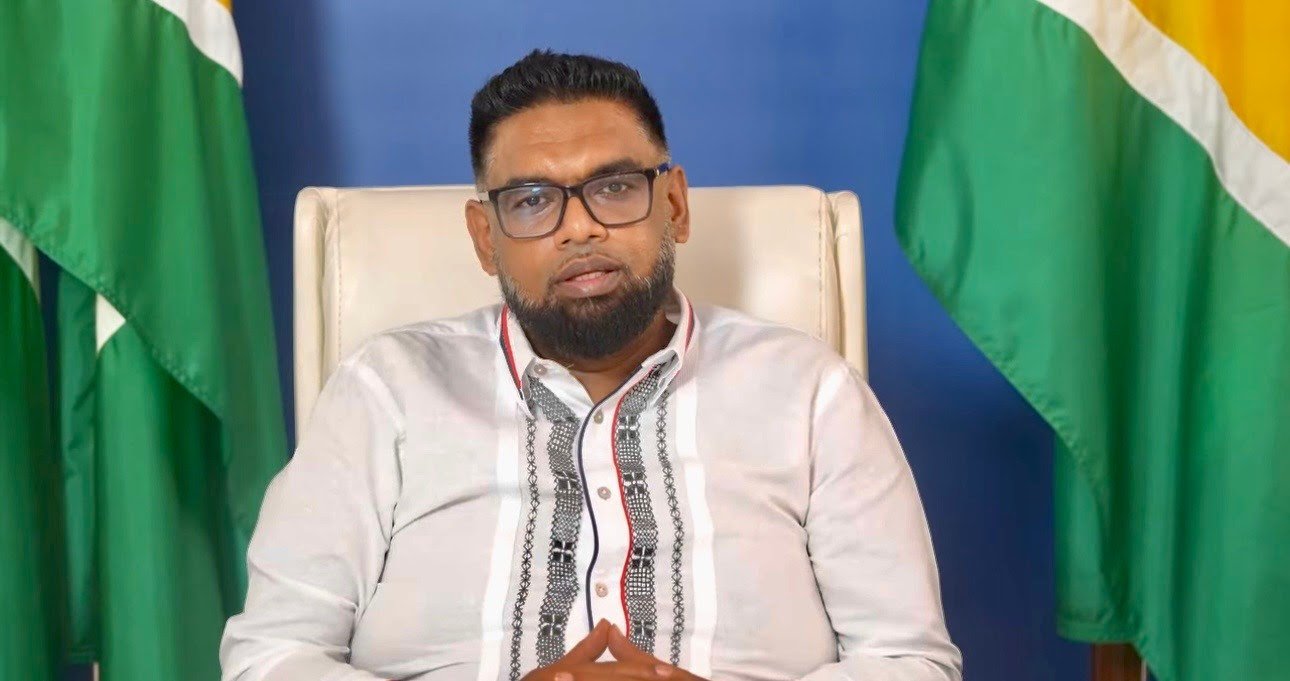
GEORGETOWN, Guyana — President Dr Mohamed Irfaan Ali has outlined Guyana’s decades-long journey from severe economic and debt distress to its current position as one of the region’s fastest-growing economies, stressing that sound economic management and policy decisions were central to the country’s transformation.
In a national address on Monday, President Ali revisited Guyana’s economic history to explain how the country moved from a period when it struggled to meet its international obligations to a position where public debt has fallen to below 30 per cent of GDP.
The President said Guyana’s severe debt crisis developed years after independence and was driven by a combination of economic policies, declining productivity, growing state ownership and increasing dependence on borrowing.
During the 1970s, the government nationalised several major industries, including bauxite and sugar, while expanding the public sector significantly. According to President Ali, declining production and the performance of loss-making state enterprises contributed to increasing borrowing and weakening economic conditions.
Between 1976 and 1988, income per person declined by 31 per cent, while inflation increased substantially. Government debt rose from 31 per cent to 475 per cent of GDP during that period, while external debt reached approximately 276 per cent of GDP by 1989.
Debt crisis and international assistance
The economic recovery process began in the late 1980s with reforms designed to restore Guyana’s relationship with international financial institutions.
When the PPP/C Administration returned to office in 1992, Guyana remained heavily indebted, with total public debt reported at 623 per cent of GDP. Debt servicing also consumed a significant share of government revenue.
Guyana subsequently entered the IMF-World Bank Heavily Indebted Poor Countries (HIPC) programme, which provided substantial debt relief while requiring reforms in areas including public finance, taxation, procurement, poverty reduction and governance.
Guyana received approximately US$410 million in debt-service relief in 1999, followed by another US$334.5 million in net present-value terms in 2003. Additional debt cancellations by the IMF, World Bank and Inter-American Development Bank in 2006 and 2007 brought further relief of approximately US$611 million.
President Ali stressed that these achievements took place well before the discovery of commercial oil, with savings from reduced debt payments helping to finance social programmes, healthcare and education.
Economic growth and social improvements
The President identified the period between 1999 and 2011 as a particularly successful phase in Guyana’s economic development, highlighting strong growth and improvements in several social indicators.
He noted that the economy expanded by a cumulative 35.3 per cent during that period, with average annual growth of approximately 4.4 per cent between 2006 and 2011.
The economic improvements were accompanied by stronger social outcomes, including primary-school enrolment remaining above 95 per cent and immunisation coverage exceeding 90 per cent.
Extreme poverty also declined, reaching 18.6 per cent by 2006, while child mortality and malnutrition rates improved.
Oil wealth changes the picture
Guyana’s economic position has strengthened further since the beginning of large-scale oil production.
President Ali pointed to a significant decline in public debt, from 47.4 per cent of GDP in 2020 to 24.3 per cent in 2024.
The IMF’s 2025 assessment placed Guyana at low risk of debt distress, an improvement from its moderate-risk assessment in 2023. The Fund projects that the country’s debt ratio could remain around 25 per cent of GDP through 2034.
According to President Ali, Guyana’s improved financial standing has also strengthened its ability to attract financing from international institutions and lenders, including US EXIM, UK Export Finance and investment funds from Qatar.
Warning against complacency
Despite the progress, President Ali warned that Guyana cannot afford to become complacent.
He said the country’s immediate challenge is no longer the threat of insolvency but ensuring that the rapid expansion of investment is managed responsibly and translates into sustained increases in productivity.
The President’s message was that Guyana’s economic transformation has been the result of a long process involving debt restructuring, fiscal reforms, economic growth and international cooperation—and that maintaining the gains will require continued discipline as the country manages its growing oil wealth.